

Equity lending webinar: how to turn your home’s value into cash flow
Most homeowners are sitting on more value than they realize. Between what’s left on the mortgage and what the home is worth today, there’s often real value that never gets used because equity lending can feel like a maze of products with different rules attached.
A home equity loan, a HELOC, a second mortgage, an equity-sharing agreement – they all borrow against the same asset, but the way each one works is genuinely different.
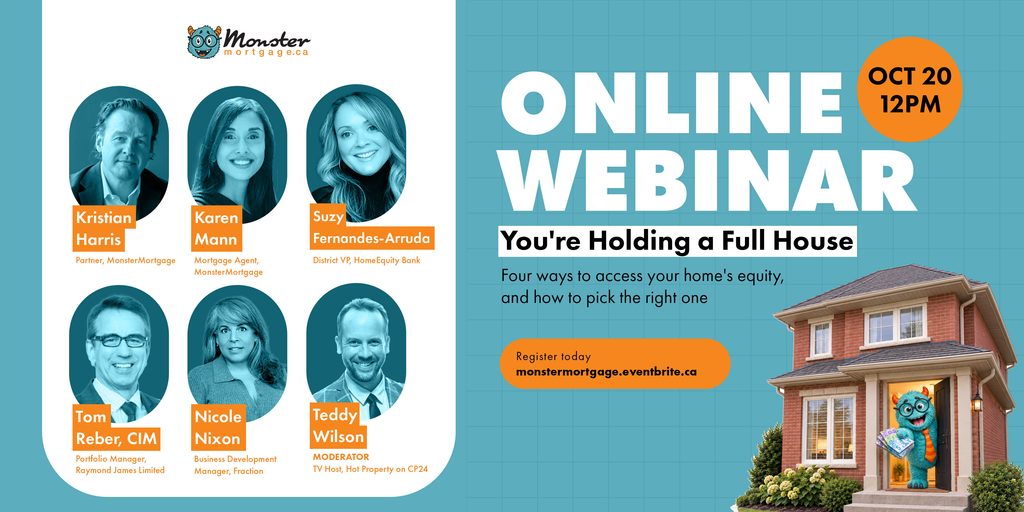
On October 20, MonsterMortgage.ca is hosting a live webinar, You’re Holding a Full House, to walk homeowners through the four main paths so you can see which one could actually apply to your situation before you talk to anyone.
What is equity lending?
Equity lending is the broad term for borrowing against the value you’ve built up in your home instead of selling it. In the GTA, where many homeowners have carried a mortgage for a decade or more through one of the steepest price run-ups in the country, that built-up value is often substantial, even in a market where average prices have pulled back over the past year.
Not every option works the same way, and that’s the part most homeowners haven’t sorted out. Some come with monthly payments, some don’t. Some check your income, others don’t. Some have an age requirement, some have none at all. The right fit depends less on the size of your equity and more on what you need the cash flow to do, and how much flexibility you want in exchange for the cost of borrowing.
Meet the panel
The webinar brings together MonsterMortgage.ca’s own team with specialists from three organizations who each work in a different corner of the equity lending space, so the conversation reflects more than one lender’s playbook.
- Kristian Harris, Partner, MonsterMortgage.ca. License #M0800314. Co-hosts and moderates, drawing on years structuring financing for GTA homeowners with self-employed, business, and non-standard income.
- Karen Mann, Mortgage Agent, MonsterMortgage.ca. Co-hosts alongside Kristian, working day to day on the GTA’s more complex equity lending files.
- Teddy Wilson, the host of CP24’s Hot Property. Moderates the panel and audience Q&A, bringing years covering the GTA real estate market on air.
- Suzy Fernandes-Arruda, District VP, HomeEquity Bank. Represents Canada’s only Schedule 1 bank focused exclusively on reverse mortgages for homeowners 55 and up.
- Nicole Nixon, Business Development Manager, Fraction. Represents the equity-sharing structure behind Canada’s first no-monthly-payment Appreciation Mortgage.
- Tom Reber, CIM, Portfolio Manager, Raymond James. Brings an independent, non-lender view of how a new equity lending payment fits into the wider financial picture.
Equity lending webinar details
When: Tuesday, October 20, 12:00–1:15pm ET
Where: Zoom, link emailed after registration
Register: monstermortgage.eventbrite.caYou can submit a question ahead of time at registration, and the panel will work submitted questions into the live Q&A alongside anything that comes up on the call.
FAQs
Is equity lending the same as refinancing?
No. Refinancing replaces your existing mortgage with a new one. Equity lending adds a second source of borrowing (or, for reverse mortgages and equity-sharing agreements, a different structure entirely) without necessarily touching your existing mortgage.
Does equity lending affect my credit score?
It can, depending on the product. Some equity lending options involve a credit check and monthly payments that report to the bureaus, while others, like reverse mortgages and equity-sharing agreements, don’t require monthly payments at all. This is one of the areas the panel compares directly.
Can self-employed or business-for-self homeowners qualify for equity lending?
Often, yes, though the income documentation differs from a salaried application. Some equity lending paths rely less on traditional income verification than others, which matters a lot for self-employed homeowners specifically.
I’m a newcomer to Canada. Does equity lending apply to me?
Yes, if you already own a home and have built up equity in it. Newcomer status doesn’t block you from tapping into your equity, it’s ownership and equity that matter. If you’re still working toward your first home, MonsterMortgage.ca’s newcomer mortgage service is the more relevant starting point.
What if I can’t make the live date and time?
Register anyway. Everyone who signs up gets the recording sent afterward, whether or not you can join live.


